Compliance that helps your business grow.
Regulation as code. Every rule linked to your policies, controls and evidence.
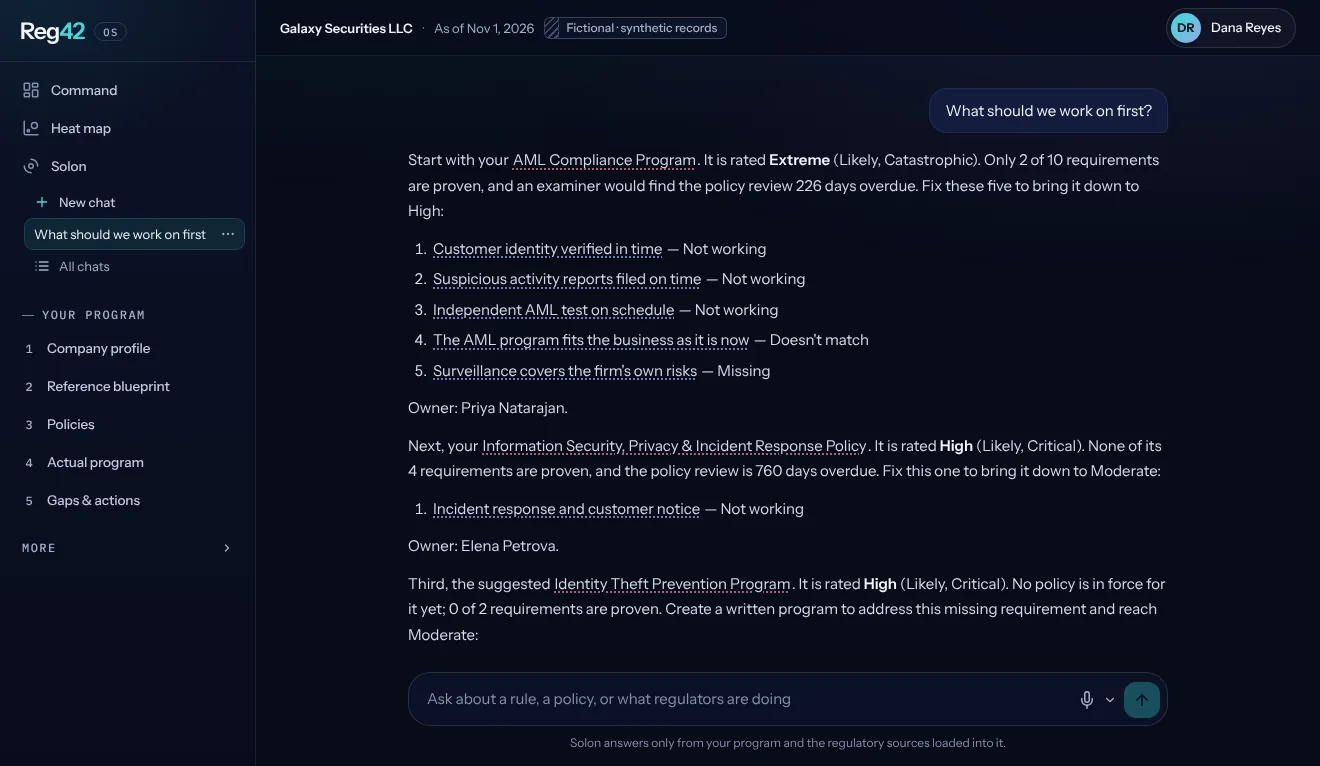
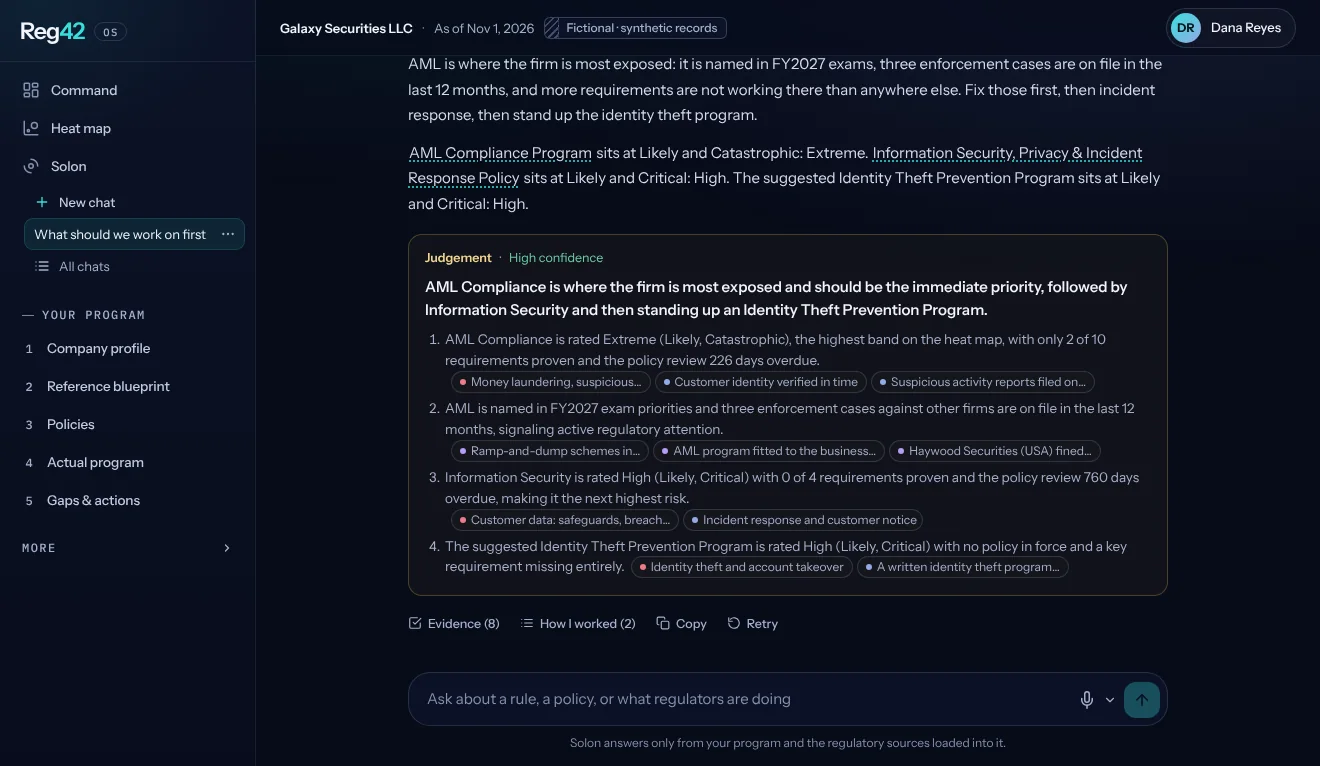
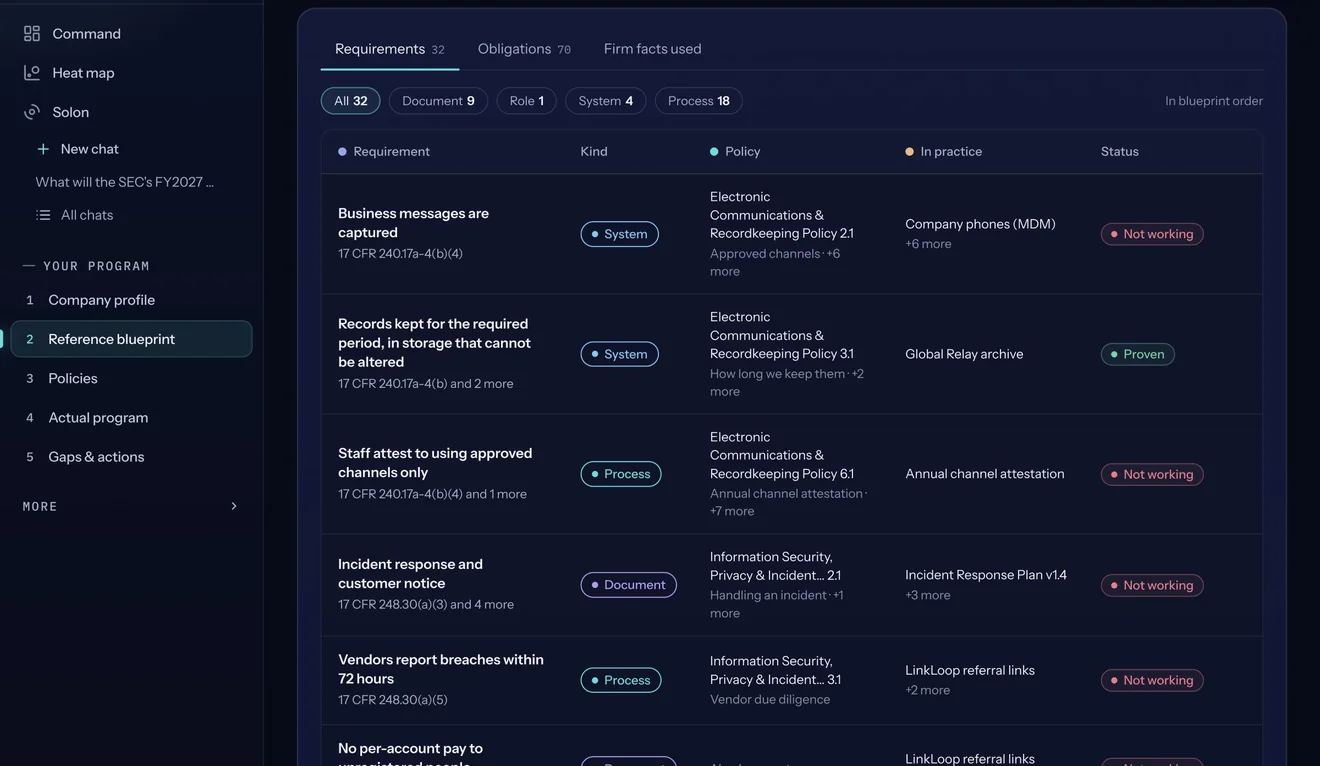
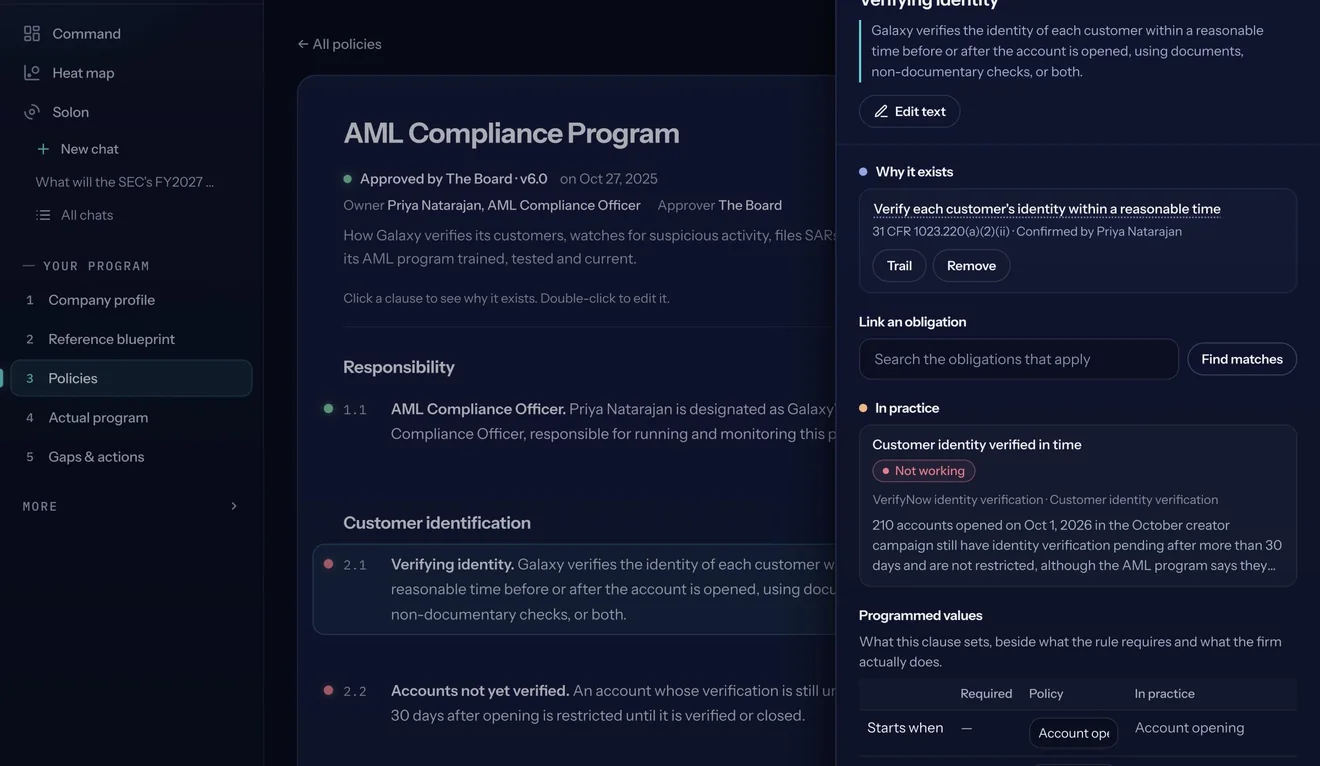
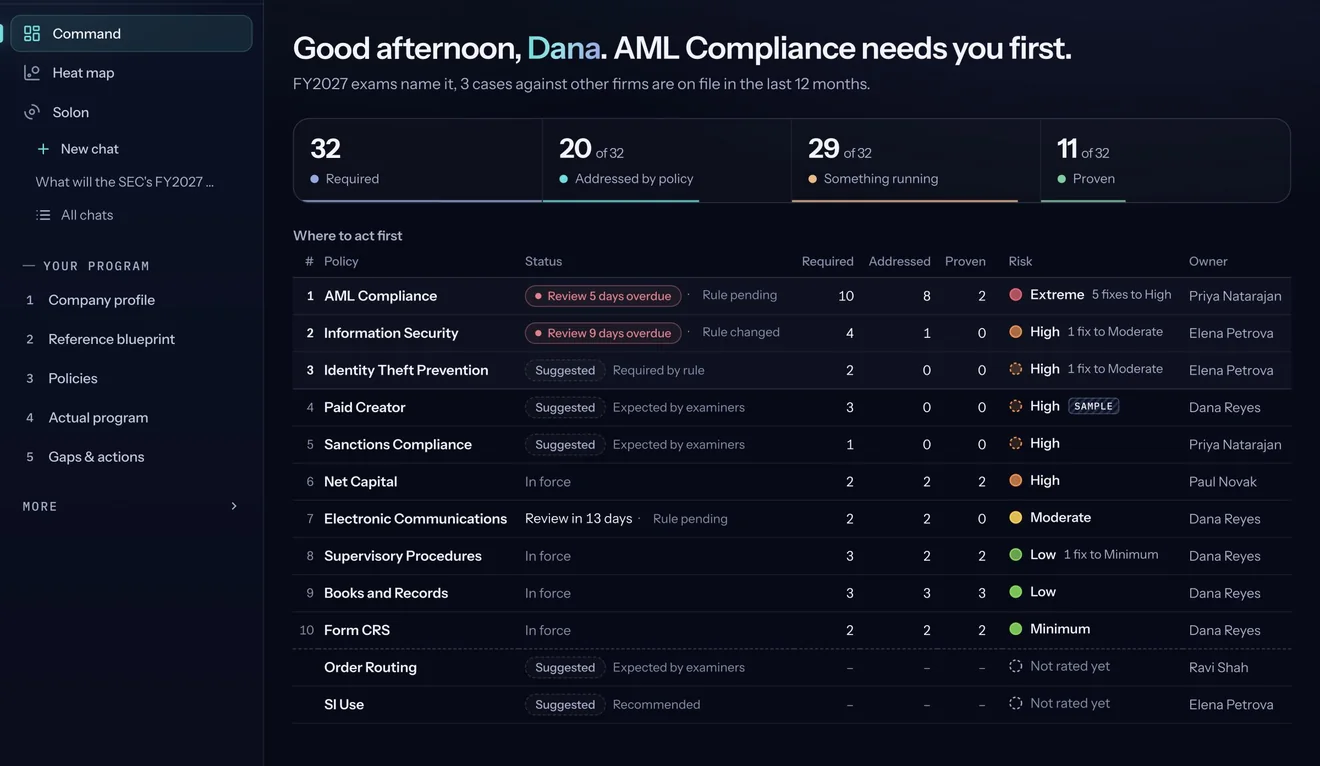
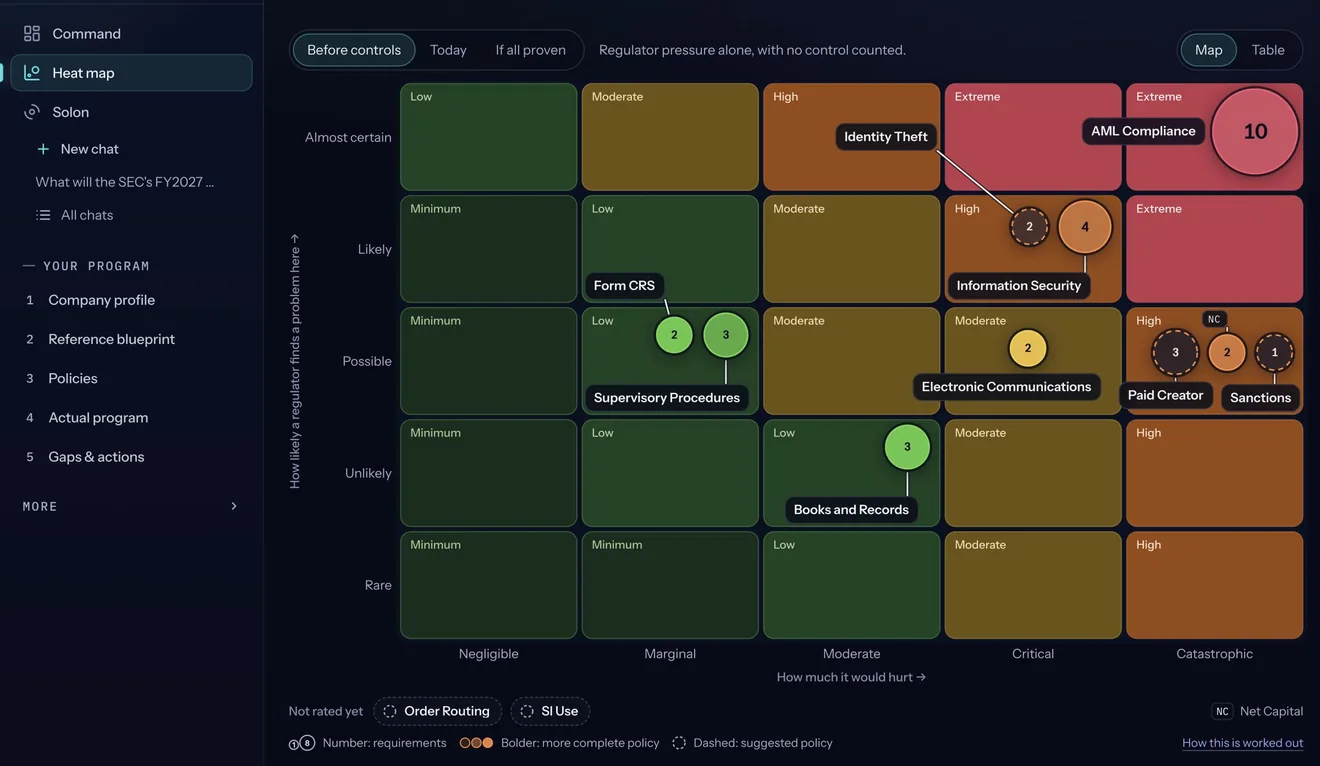
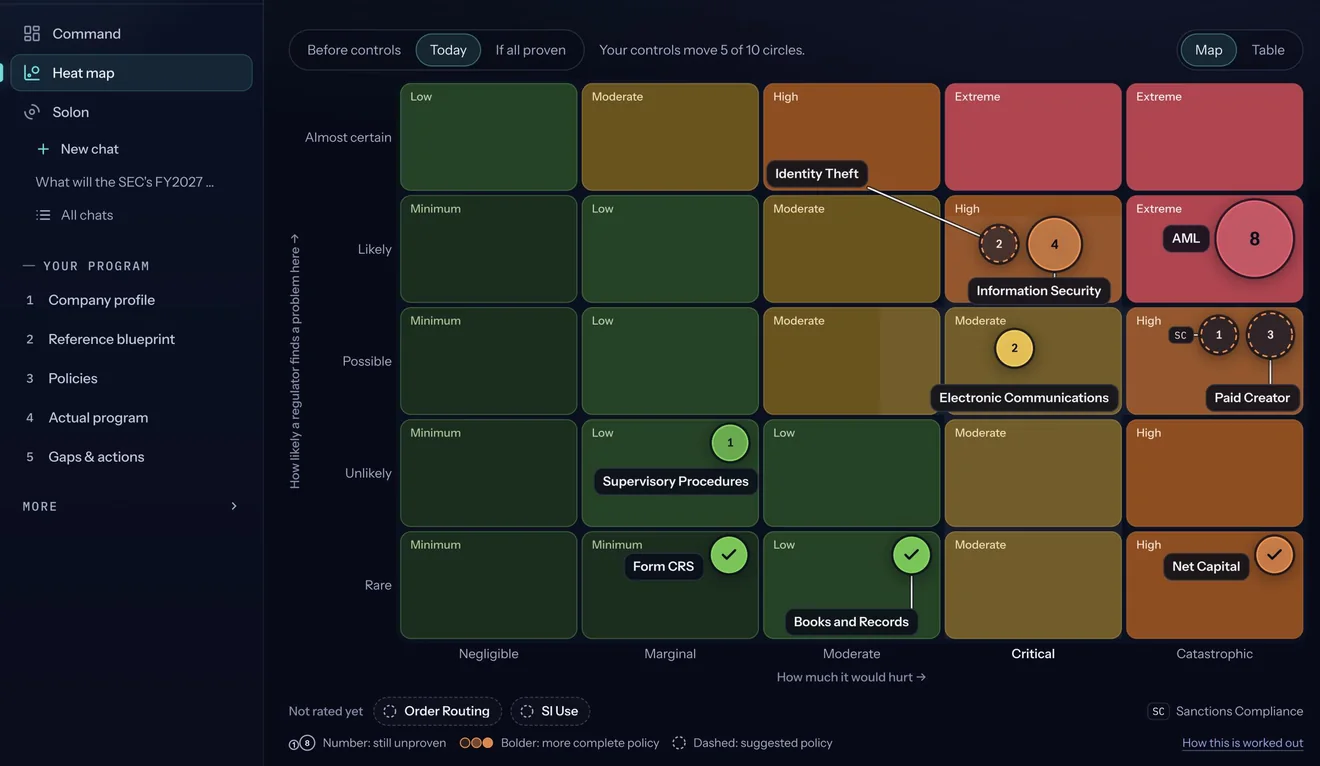
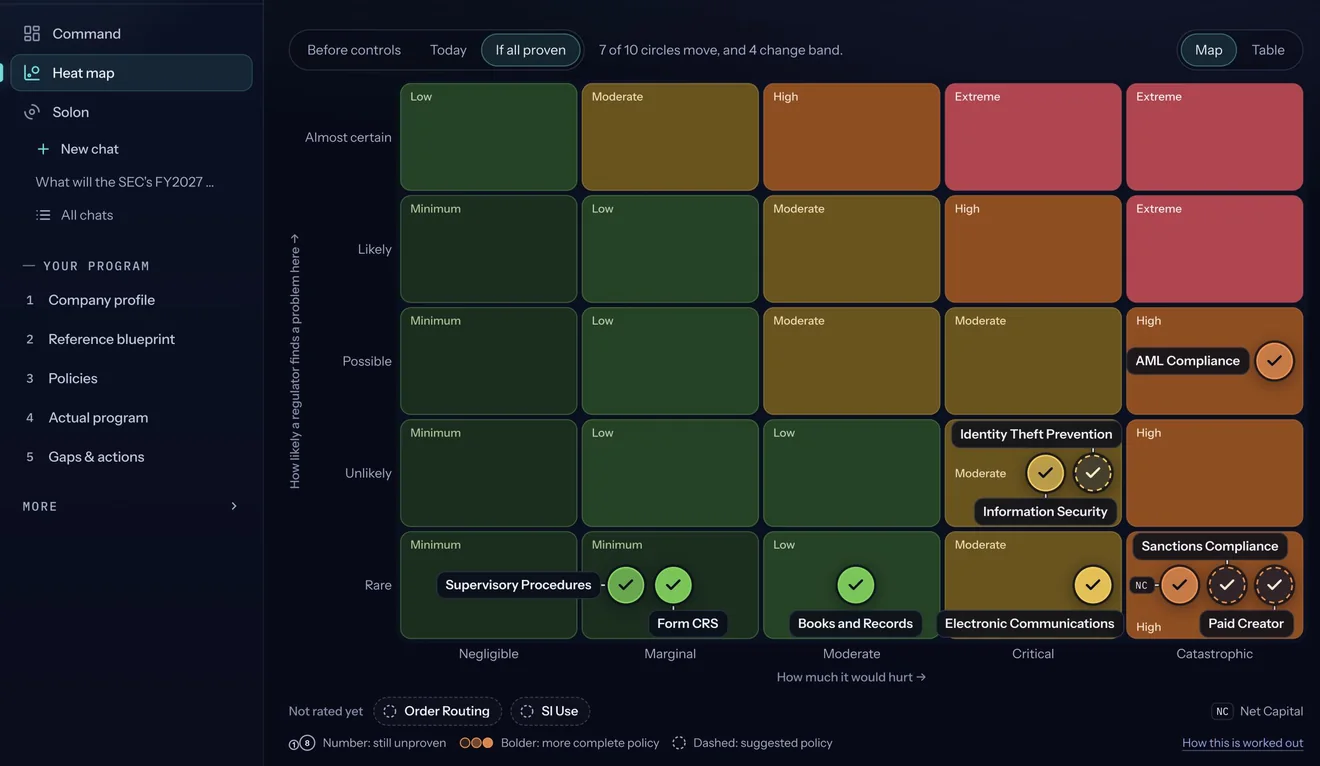
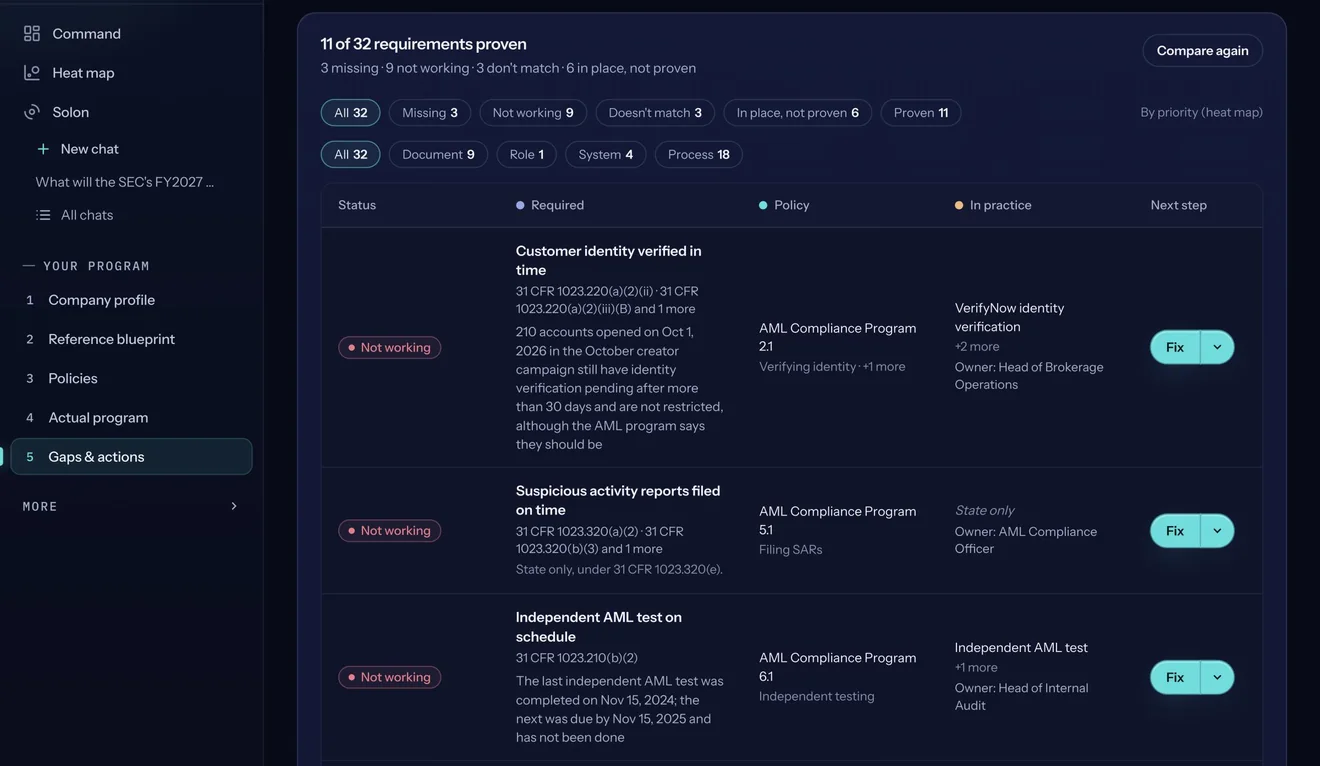
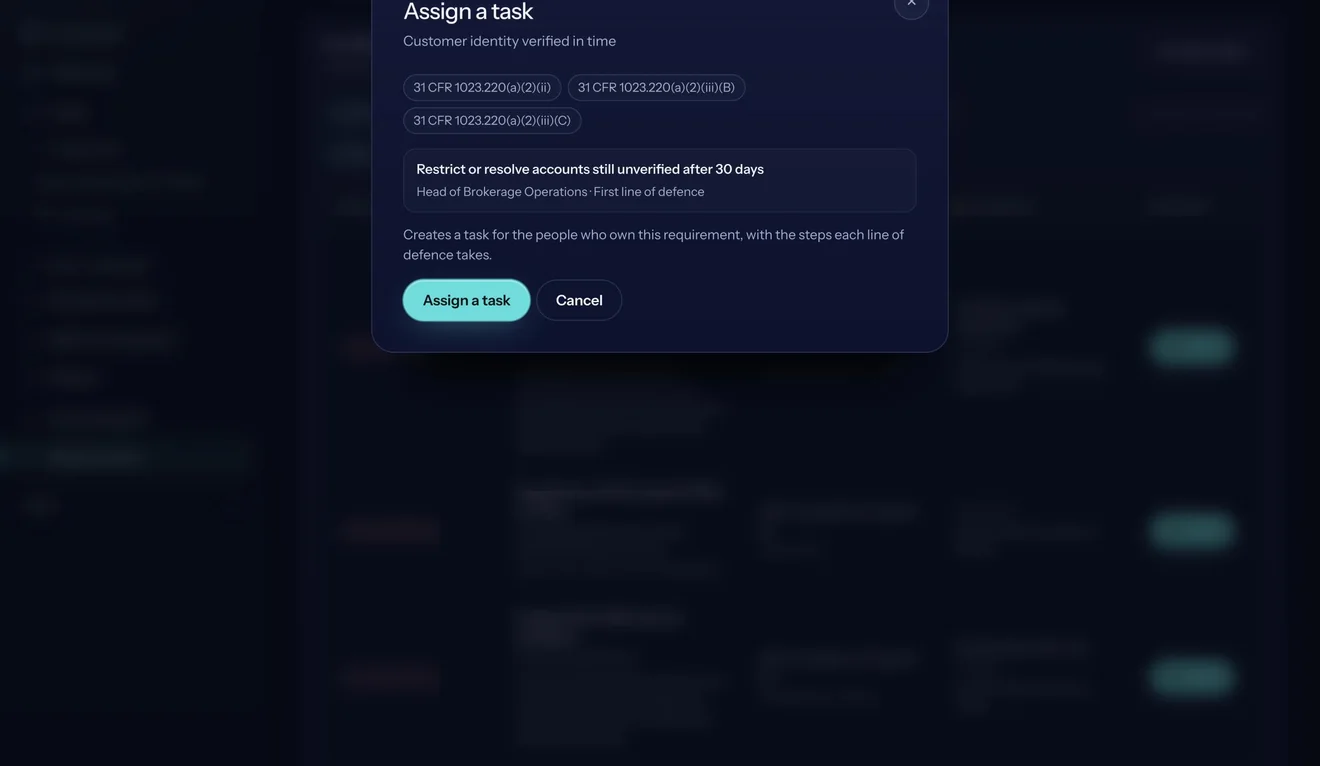
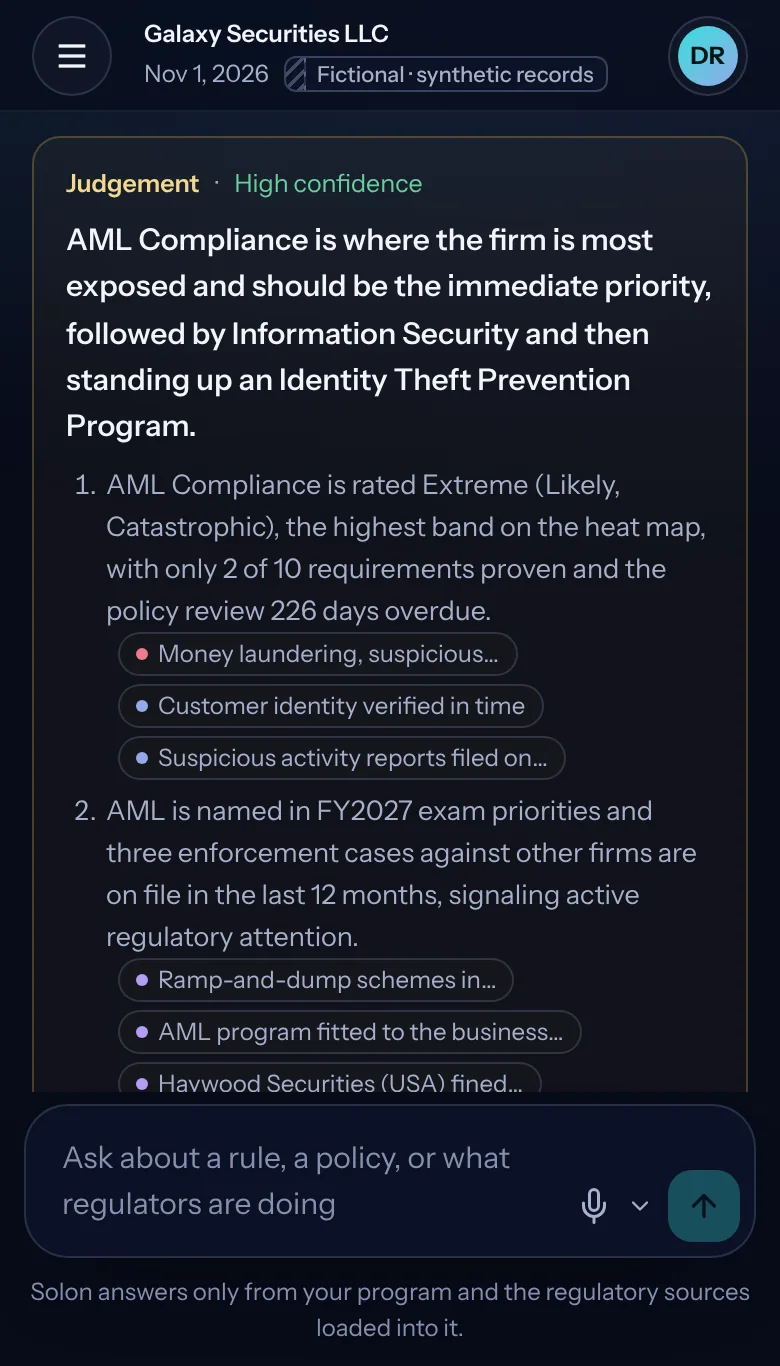
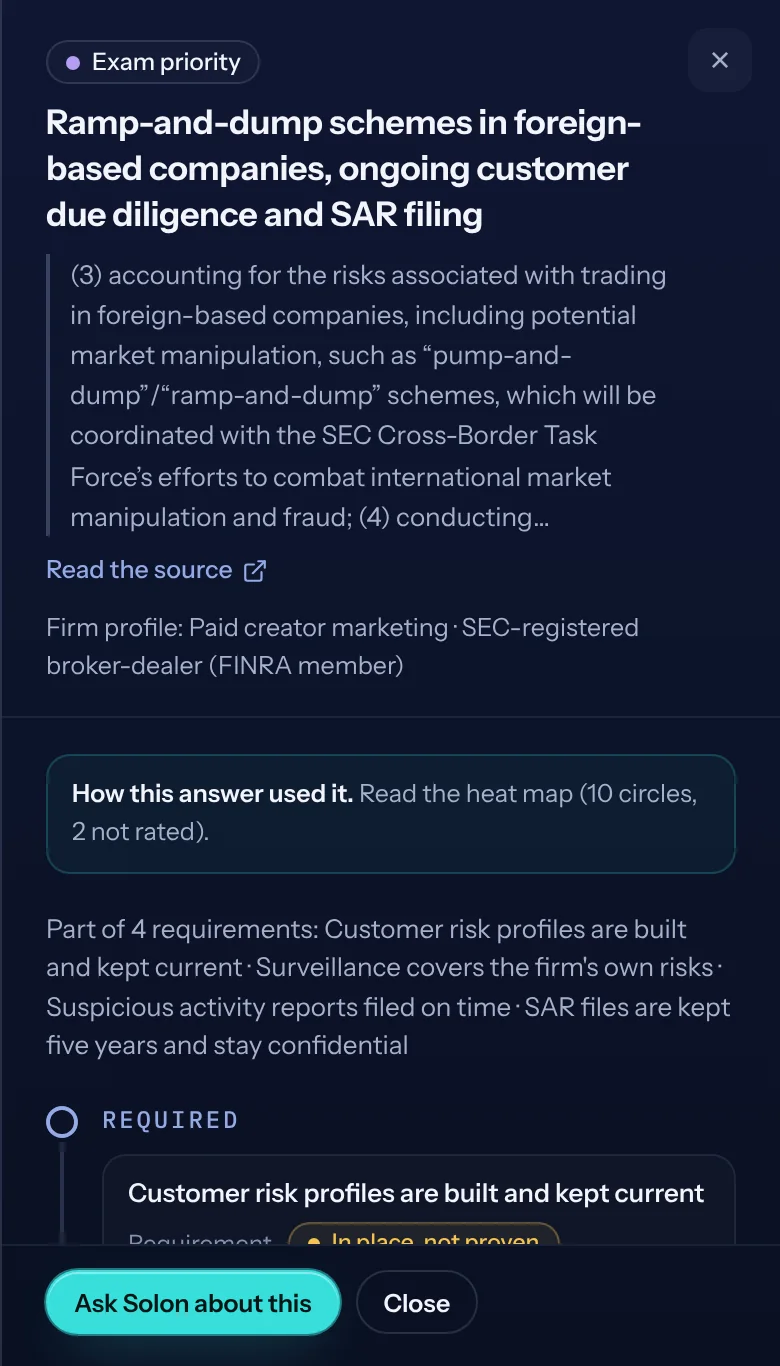
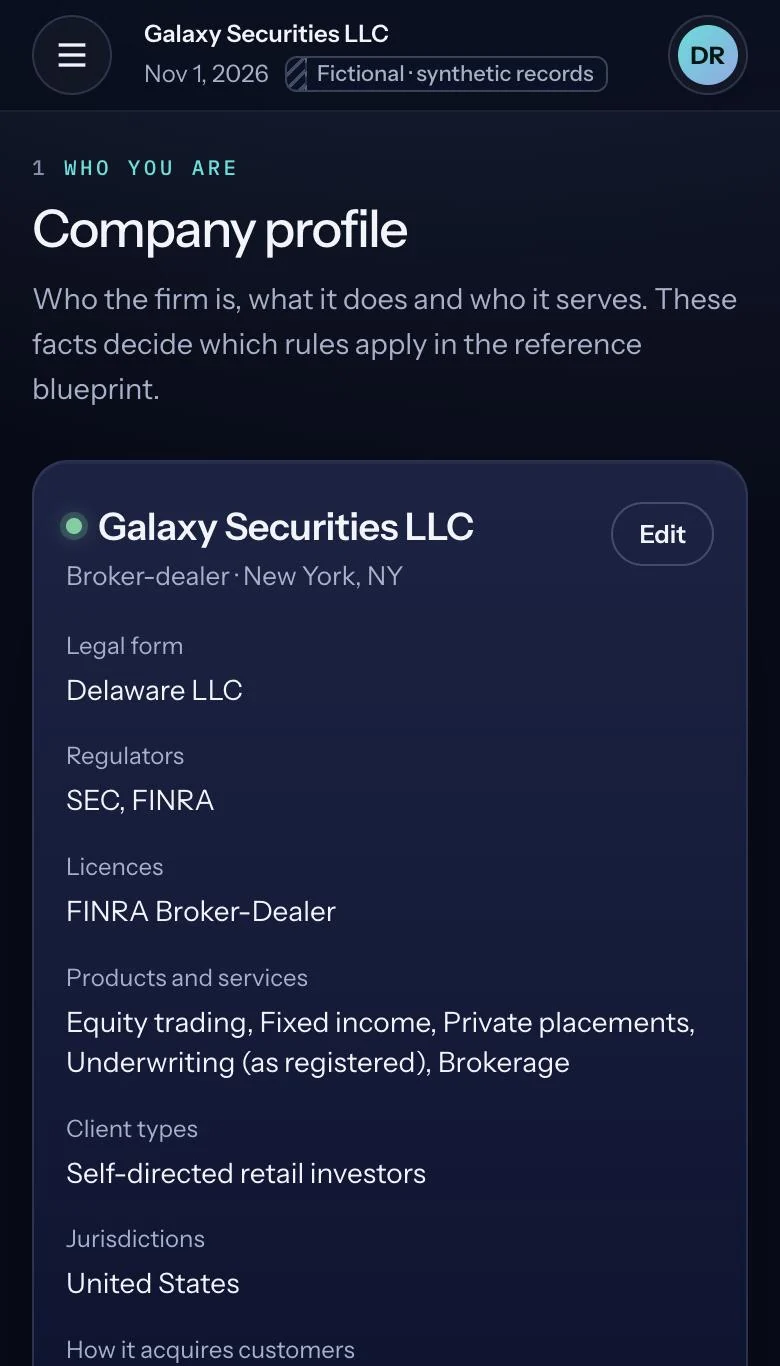
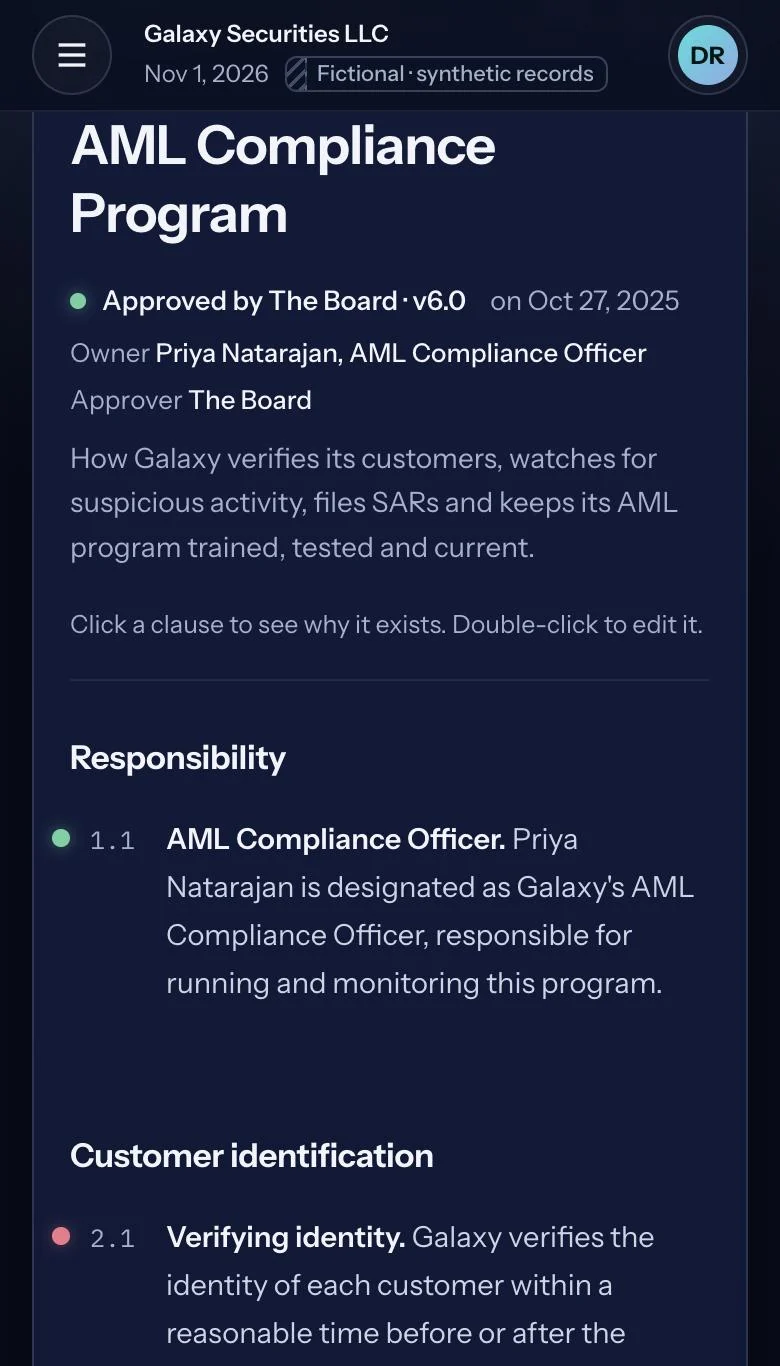
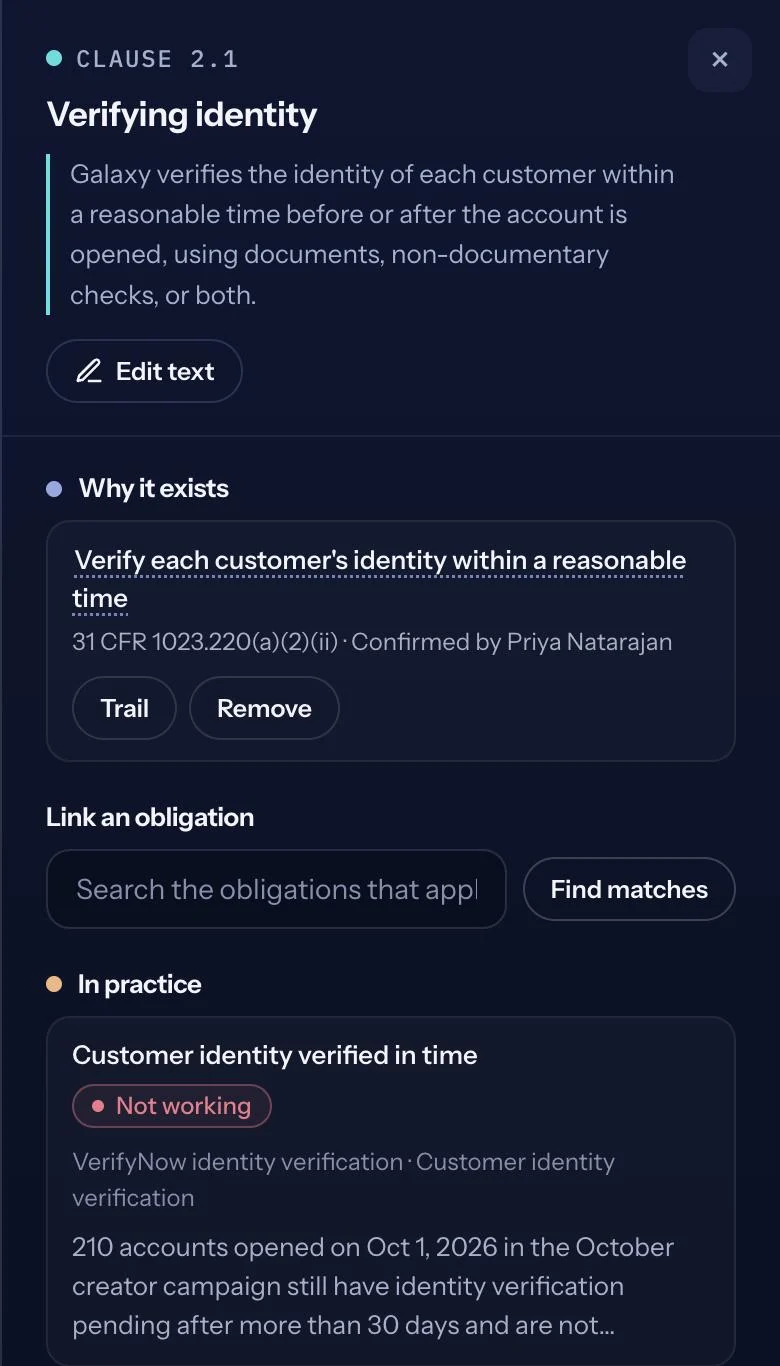
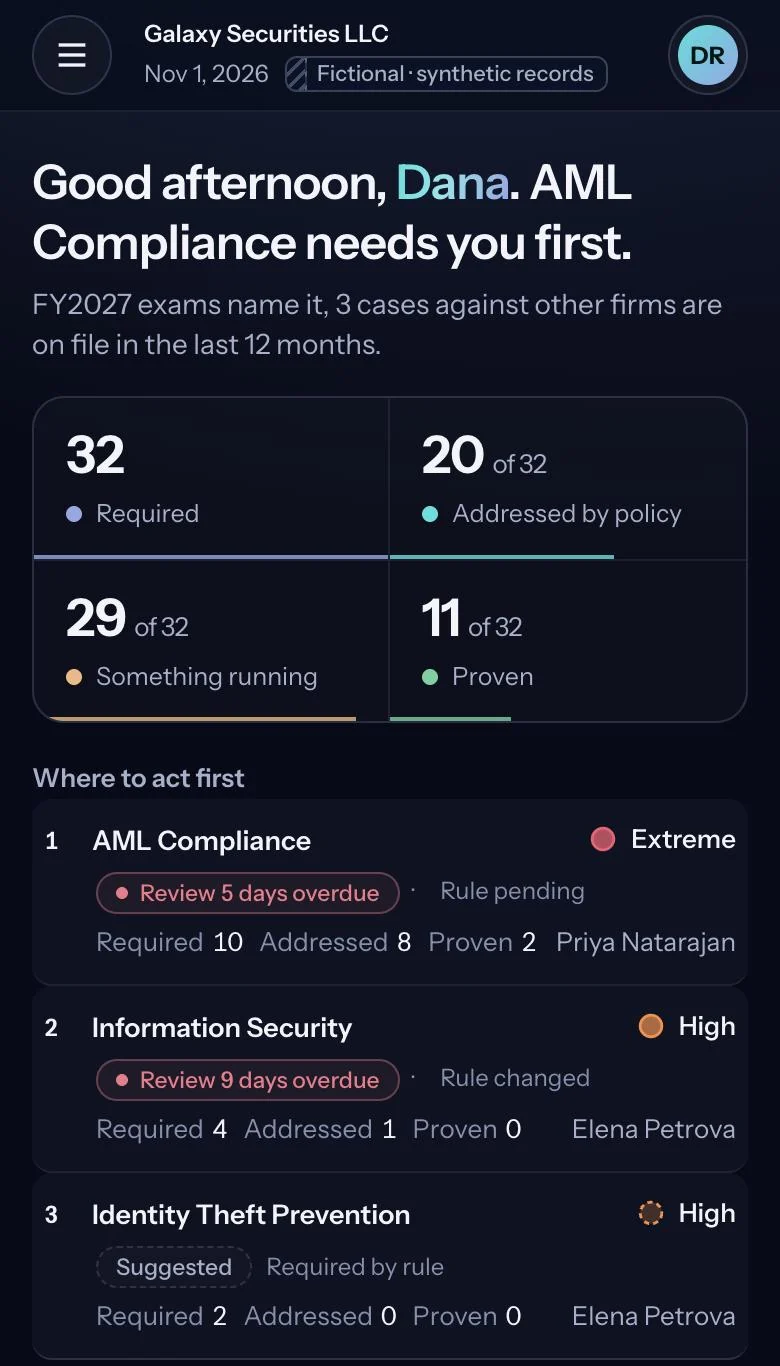
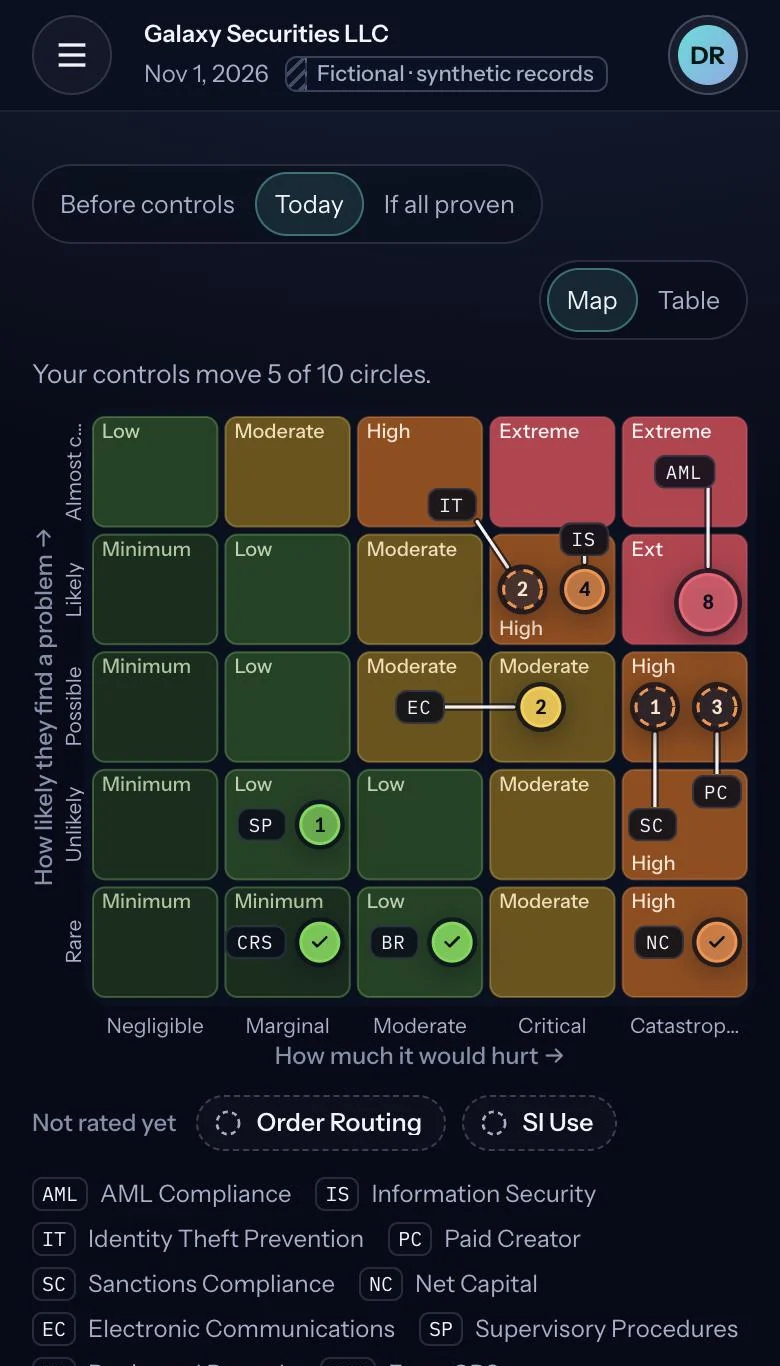
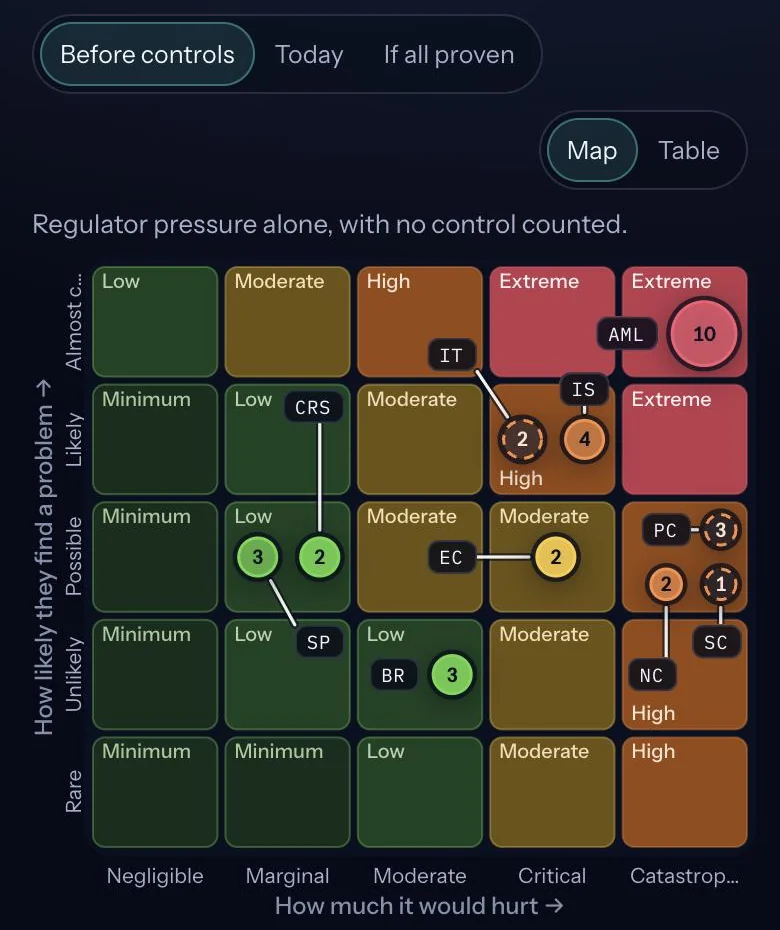
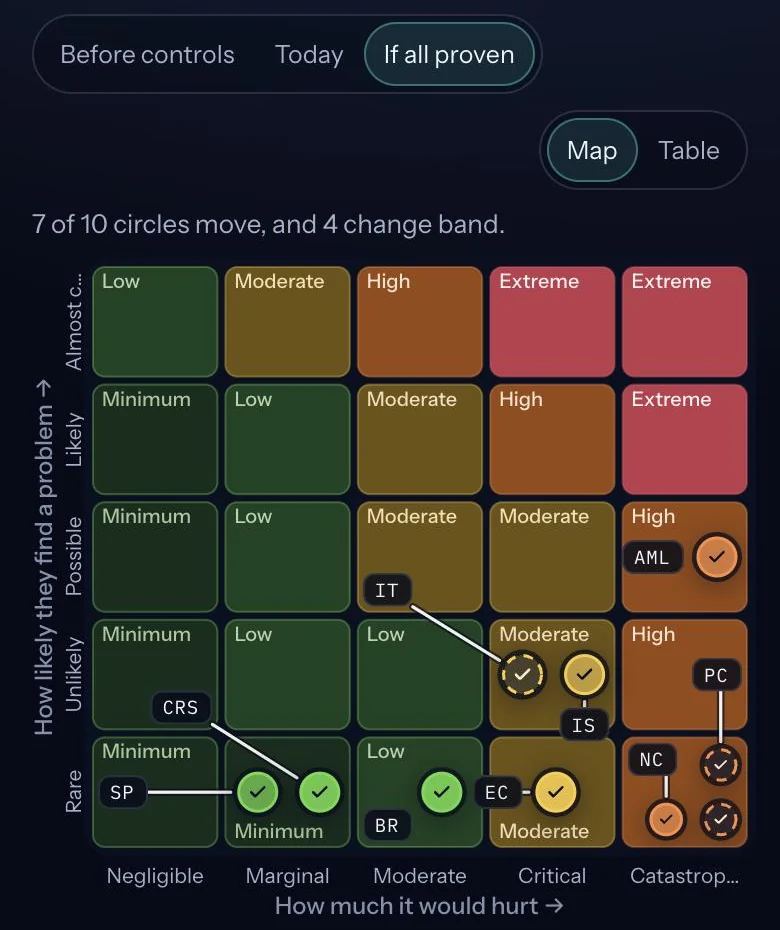
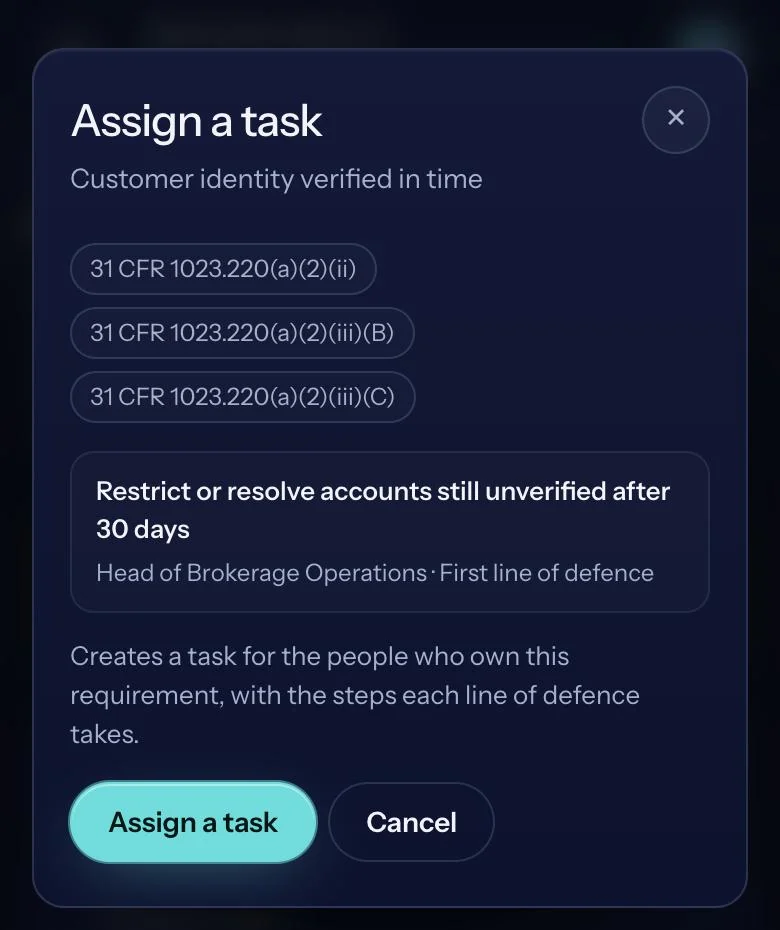
Ask Solon. Ask about a rule, a policy or what regulators are doing. Every reason shows its evidence.
Real screens of the product, on a fictional firm with synthetic records.
What we solve for a chief compliance officer
Defense
Today Risks scattered across spreadsheets, tools and people.
With Reg42 Every risk in one live view, with its evidence.
Efficiency
Today Mapping and evidence by hand. 42% of C-suite time at large US banks went to compliance in 2023.1
With Reg42 Solon does the work and shows its evidence. Your people decide.
Growth
Today New markets, licenses and products wait on compliance.
With Reg42 See what they require against what you have, before you commit.
1. Bank Policy Institute survey of 20 member banks, October 2024.
Solon reads only from evidence.
Our compliance AI reads your firm through CLHEAR, as one graph you can trust.
| A general AI model | Solon | |
|---|---|---|
| Reads from | Its training data, the web and your data, with no context graph for compliance | Your data, through CLHEAR, as one compliance graph |
| Shows | An answer with source links, not structured as a compliance graph, so less consistent and reliable | The answer, with the rules, policies and evidence behind it |
| Without evidence | May still answer | Says it doesn’t know |
| Kept current | Gathers its context again for each question | The graph keeps the latest context |
CLHEAR is regulation, written as code.
Eight layers, from the rule to your program.
The rules
- L1SourcesOfficial sources: rules, enforcement, news, Q&As, directives.
- L2DutiesEach duty restates one or more obligations in plain words.
- L3Building blocksWhat each duty takes in practice.
The firm
- L4ProfilesEvery firm profile the rules can apply to.
- L5ActivitiesThe business and compliance work the firm runs.
The program
- L6BlueprintThe program a profile calls for, traced to each clause.
- L7Risk scoresExposure per duty, from regulators and your own data.
- L8Best practicesHow others comply well: examples, templates, Q&As.
Map, Compare, Comply
Three steps onto Reg42.
- MapConnect your policies, controls and evidence.
- CompareSee what the rules require, and what is missing.
- ComplyClose each gap with an owner. Keep the proof.
A letter from our founder
“The intelligence has arrived. Nobody has onboarded it.”
 Avner Yoffe, Co-founder and CEO
Questions and answers
Who is Reg42 for?
Chief compliance officers and their teams, at banks and other regulated financial firms.
What is CLHEAR?
Our language for compliance: each rule, its duties and what they require, as code. It is patent pending in the US.
What does Solon answer from?
Only your compliance graph. Without evidence, Solon says it doesn’t know.
Where does our data live?
In a dedicated AWS account run by Reg42, or in your own cloud.
Who makes the decisions?
Your people. Solon answers with its evidence; your people review and sign.
See Solon at work
Tell us your domain. We will show you Solon on it.